AI predictions for sports betting in Great Britain: what they are, what they cost, and why no tip is ever certain
 Available in US
*Current as of 27 October 2026 — verified against the Gambling Commission’s public register.*
The phrase sounds like a shortcut: feed the fixtures into a model, let the machine name the winners, sit back and collect. The reality is duller and harder to set aside, and this guide is built around it. A prediction is a probability dressed as a pick. A bookmaker’s odds are a probability dressed as a price. The space between the two is where any edge lives, and that space is small, contested, and never guaranteed. AI changes the speed at which numbers are crunched, not the rule that the future cannot be known in advance.
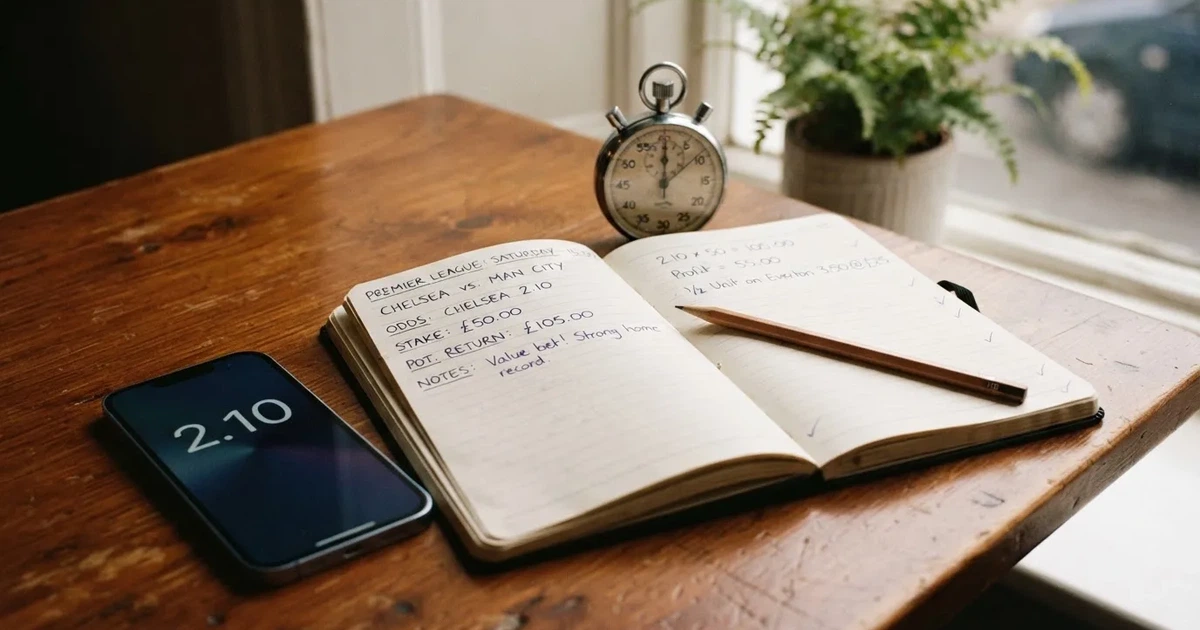
What follows is a guide rather than a tip sheet. It explains how a model turns form, statistics, line-ups and market data into a probability, how the bookmaker’s margin eats into every price, what a value bet actually is, and why a tip — whether it comes from a human tipster or a neural net — is always a bet, not a promise. The British licensing frame is described in full because it decides who can offer odds in Great Britain and what protections attach. The ranking that follows compares ten Gambling Commission-licensed operators on the matters a punter weighing them against each other needs in front of them.
The angle of this page is choice: which paths exist for a British punter interested in AI-driven predictions, what each one suits, and what each one costs. Where a path contradicts a brand’s profile, that mismatch is named. Where the marketing is ahead of the substance, the substance is what the page reports.
What an AI prediction actually is
An AI prediction is the output of a model that has been trained on historical data — past results, player statistics, head-to-head records, even weather and travel patterns — and that produces a probability for each outcome of an event. “Win” is rarely the model’s vocabulary. The model assigns each team, horse or player a percentage chance, and the punter’s job is to compare that percentage to the price the bookmaker is offering.
A price in decimal odds already encodes a probability. Odds of 2.00 imply a 50% chance; odds of 4.00 imply a 25% chance; odds of 1.50 imply a 66.7% chance. The conversion is one over the decimal odds, so the implied probability of any price is 1 ÷ odds. A model that says a side has a 55% chance of winning is, in punter language, saying the price should be shorter than 1.82 (because 1 ÷ 0.55 = 1.82). If the bookmaker offers 2.00 or longer, the model’s percentage sits above the price’s implied percentage, and that gap is what a value bet is.
The difference between a human tipster and an AI tipster is mostly one of plumbing. A human reads form, watches injuries, calls on memory and instinct, and produces a selection. A model reads the same inputs as columns of numbers, weights them by some learned or specified importance, and produces a percentage. Both are fallible. Both miss the dressing-room story, the player carrying a knock, the manager protecting a cup tie. Both can be wrong about the same fixture in the same week. The model scales — it can price every Premier League game in a Sunday afternoon — and that scale is its genuine advantage. The punter who reads one column in one newspaper has neither the time nor the data to do that.
Three things follow from this:
- The output is a probability, not a prediction in the conversational sense. Saying “the model gives Arsenal a 62% chance” is a different statement from “Arsenal will win”. The 38% matters more than the 62% in a betting context, because the 38% is the bet’s price of admission.
- The bookmaker’s margin is on the other side of the trade. Whatever price is on the screen has already been squeezed so the bookmaker keeps a slice on every outcome. The 62% Arsenal chance at odds of 1.55 (implied 64.5%) is not a value bet; the same 62% at odds of 1.75 (implied 57.1%) might be. The model is only half the calculation; the price is the other half.
- The same model that says Arsenal are 62% to win will, on a quiet weekend, say the same thing about four other matches the punter has no stake in. The selective use of a model’s output — picking the games where it agrees with the price and ignoring the rest — is the part the marketing usually skips.
How a prediction is built
The inputs that feed most published football and racing models are not exotic. Recent form (the last five or six results, weighted so a win last Tuesday counts for more than one in October), expected goals or expected goals against (xG and xGA) at the team and player level, shots and shots on target, head-to-head history over a chosen window, the venue, the line-ups where known, and any news that the model has been told to take seriously (injuries, suspensions, weather). Horse racing models add going, distance suitability, draw bias at the course, the jockey-trainer combination, and the market’s own drift or steam in the minutes before the off.
What the model does with the inputs varies. A logistic regression is a long way from a gradient-boosted tree, which is a long way from a recurrent neural net trained on tracking data. The differences in published accuracy are smaller than the marketing suggests. Each approach has its failure modes: a regression is blunt, a tree overfits to the league it was trained on, a neural net requires far more data than most British racing fixtures provide. The skill of the builder matters more than the architecture, and the calibration matters more than the headline accuracy.
Why no tip is ever certain
A probability is not a guarantee. A 70% favourite loses three times in ten on average, and the punter who backs every 70% favourite at flat stakes without thinking about the price is still expected to lose — because the bookmaker’s margin ensures that the price of a 70% chance is shorter than 1.43, and the model’s calibration is rarely perfect. Streaks happen. Variance is the silent partner of every punter’s bank.
The headline risk is not the wrong result but the wrong framing. A model that is right 60% of the time at 1.80 implied prices is bleeding money; a model that is right 55% of the time at 2.20 implied prices is in profit. The percentage of winners is a number for the marketing; the yield against the bookmaker’s margin is the number for the bank.
Free bet ai, free sports betting ai and the live betting ai market
Three search terms cluster around this subject, and they describe three different products rather than three synonyms. A “free bet ai” is a service that gives selections on the house, usually paid for by an affiliate link to a bookmaker — the tip is the marketing, the subscription or the click is the revenue. A “free sports betting ai” is the same idea with a sport-specific wrapper: free Premier League tips, free Champions League picks, free racing naps. A “live betting ai” is a different beast — it prices events in play, usually second by second, and the punter’s edge, if any, comes from reacting faster than the model to a goal, a red card or a sudden weather change. Live markets have thinner margins than pre-match on most books and a different house edge in practice, because the price moves as the model updates and the laggards get punished.
Each carries the same caveat. The free product is free because the seller is paid by someone else, and that someone else is usually the bookmaker the tip is steering you towards. The live product trades a thin edge for a wide variance and a clock that never stops. Both are bets against the bookmaker’s margin with whatever speed and discipline the punter can bring.
The law in Great Britain: where AI predictions meet the Gambling Act
The legal frame around sports betting in Great Britain is short to state and wide in its consequences. The Gambling Commission licenses the whole commercial market under the Gambling Act 2005. The Commission is a non-departmental public body sponsored by the Department for Culture, Media and Sport. The Act covers England, Scotland and Wales; Northern Ireland runs its own older law, and a Great Britain licence does not regulate Northern Ireland.
Since the Gambling (Licensing and Advertising) Act 2014, an operator whose remote facilities are used in Great Britain needs a Commission licence wherever it is based. Sections 33 and 36 of the 2005 Act, as amended, are the relevant provisions; a Curaçao, Maltese or Gibraltar licence is not a substitute for serving British customers. There is no cap on the number of licences the Commission can issue, and there is no state monopoly. The market is open, the regulator is specific, and the test of whether a brand holds a licence is the Commission’s own public register.
The public register is searchable by business name, trading name, domain or account number, and it is the only place a licence claim can be checked against. Licensed operators commonly use a .com as well as a .co.uk address, so the domain alone proves nothing. A brand that claims to be “licensed in the UK” without naming an account number is asking the punter to do the check; a brand that names the number is doing it for them. The ten operators compared further down each name an account number from the Commission’s register.
Betting licence types the punter meets
Five categories of remote betting licence cover the market a British punter bets into:
- Remote general betting standard (real events). The workhorse category, covering sports betting on actual fixtures.
- Remote general betting standard (virtual events). A separate category for computer-generated events, often branded as virtual football or virtual racing.
- Remote general betting limited. A smaller-scale category with conditions on stake and turnover.
- Remote pool betting. The licence behind pool betting on horse and dog racing off-course.
- Remote betting intermediary. The exchange licence, behind Betfair and any other back-and-lay platform.
Several brands run under one licensee — Ladbrokes and Coral share a parent, Paddy Power and Betfair share one — and the register, not the front page, is what to trust on that point. The brands compared in this guide are each licensed separately on the register.
Financial spread betting is regulated by the Financial Conduct Authority rather than the Commission, and a punter using a spread-betting product is in a different regulatory frame altogether. Spreadex, for example, is regulated by the FCA for spread betting and by the Gambling Commission for fixed-odds betting, and its own materials note that spread betting losses can exceed deposits — a line worth reading before opening the account, because spread-betting losses are not capped by the stake the way a fixed-odds bet is.
Age and identity
The minimum age for any gambling product in Great Britain is 18. A licensed operator must verify the customer’s name, address and date of birth before the first deposit, and that requirement has been in force since 7 May 2019. The verification applies to free bets and bonuses as well as to cash stakes — a free bet is not a route around the check. There is no anonymous play at a licensed site. Higher-staked customers should expect source-of-funds questions under the money-laundering rules, and those are normal rather than punitive.
Bonuses and wagering: the 10x cap
Two promotional rules changed the British market in 2026. The first, in force since 19 January 2026, caps wagering requirements on bonuses at 10x — a £10 bonus at 50x wagering, which used to need £500 of qualifying bets, now needs no more than £100 of qualifying bets before the bonus and any winnings tied to it can be withdrawn. The second, also in force since the same date, bans mixed-product promotions: an offer that requires gambling on two or more product types — betting, casino, bingo, lottery — can no longer be advertised at all, so “bet on football to get free spins” is no longer a legal proposition at a GB-licensed site.
Whether the 10x cap applies to a free bet with no wagering condition, and any cap on the money value of a bonus, are not established in the published guidance. A punter reading the small print on a welcome offer should look for the wagering multiple, the minimum odds for qualifying bets, the expiry on the free bet and any cap on winnings from a free bet — those four numbers tell almost the whole story, and the small print is where they live.
Tax
The British punter pays no tax on betting winnings. General Betting Duty is the operator’s tax, currently 15% on gross profits. From 1 April 2027 a new remote betting rate of 25% applies within General Betting Duty, while remote bets on UK horse racing, bets on self-machine terminals in licensed premises, pool betting and in-person betting stay at 15%. Whether operators pass duty on through shorter odds is not established, and a punter reading a price list should not assume that duty is being passed through. The Commission’s statutory levy is a separate charge on operators and not a tax the punter pays.
Credit cards
Credit cards have been banned for gambling in Great Britain since 14 April 2020. The ban extends to credit-card-funded payments through an e-wallet, so a punter cannot route a credit-card deposit through PayPal or a similar service. Debit cards and bank-based payments are not covered by the ban. E-wallets and bank transfers are common at the licensed operators compared below, and the absence of credit cards is uniform across the licensed market.
Advertising
The Commission does not license advertising; marketing runs through the CAP Code for non-broadcast and the BCAP Code for broadcast, both enforced by the ASA, alongside the Commission’s own LCCP marketing conditions. CAP Code section 16 is the rule most often quoted: marketing must be socially responsible, must not have strong appeal to under-18s, and no one who is or seems to be under 25 may appear gambling or play a significant role in the advertisement. The rule concerns who can be in the ad, not who can place the bet, but it is the rule that has reshaped the front of British gambling advertising over the last decade. Whistle-to-whistle — the absence of betting ads on TV from five minutes before a live sporting event to five minutes after it, before the 9pm watershed — is an industry code rather than a statute, and it has been in place since 1 August 2019, with horse and greyhound racing excluded.
The Premier League clubs’ voluntary withdrawal of gambling sponsorship from the front of matchday shirts, in place from the 2026/27 season, is a commercial decision rather than a legal one. Sleeves and pitch-side hoardings remain. Operators are responsible for marketing by their affiliates, which is the legal hook behind the affiliate disclosure rules on bonus pages and review sites.
Offshore and unlicensed brands
A Great Britain licence is compulsory at the point of consumption, not the point of incorporation. Providing gambling facilities in Great Britain without the licence the Act requires is an offence under section 33 of the Gambling Act 2005 — on summary conviction up to 51 weeks’ imprisonment, a fine up to level 5, or both, with six months’ imprisonment in Scotland. The offence is aimed at the operator, not the customer. No offence aimed at the customer who merely bets on an unlicensed site was found in the statute.
That legal posture is not a clean bill of health for the punter who chooses an offshore brand. The loss of protection is wide. No GAMSTOP coverage. No Commission complaints route. No approved dispute-resolution body. No British consumer redress if funds are withheld. None of the bonus controls that apply to a GB-licensed welcome offer. None of the financial vulnerability checks. None of the identity verification standards. Enforcement at the Commission end is disruption rather than blocking — cease-and-desist notices, search-engine referrals, work with registrars, hosts and payment providers — and the Commission has been given, or is about to receive, court-order DNS blocking powers, but ISP-level blocking is not in operation at the time of writing.
The honest framing is two-sided. A licensed brand offers the checks, the limits, the GAMSTOP membership and the bonus cap; it also requires the verification before the first deposit. An unlicensed brand offers none of those protections and the possibility of a fund being withheld. Neither is automatically the safer choice — the licensed brand takes the verification friction and the frozen-step exemptions, the unlicensed brand takes the loss of recourse.
Responsible gambling: the protections that come with the licence
Every GB-licensed online operator is a GAMSTOP member. The self-exclusion scheme has been a mandatory licence condition for online operators since 31 March 2020, and the periods on offer are six months, one year, five years, or five years with auto-renewal. After the minimum period, the exclusion stays in place for a further seven years unless the customer asks GAMSTOP to remove it. GAMSTOP covers online sites and apps; betting shops use a separate offline scheme.
Three operator-side controls are now uniform across the licensed market.
Deposit limits. Operators must offer a gross deposit limit on a fixed time frame. The first phase of changes applied from 31 October 2025; a second phase was postponed to 30 September 2026, and whether that second phase is live at the time of writing is not established. Limits are the customer’s choice — there is no state-set ceiling on deposits or losses for betting, only the customer’s own choice of how much to allow themselves.
Financial vulnerability check. Under LCCP condition 3.4.4, in force since 30 August 2024, a licensed remote betting operator runs a public-record check — for example, bankruptcy or county court judgments — when a customer’s deposits minus withdrawals exceed £150 in a rolling 30-day window, with the threshold live since 28 February 2025. The check is a public-record check rather than an income check or a credit-reference check. A punter who spends modestly will not encounter it; a punter whose net deposits clear £150 in a rolling month should expect it.
Financial risk assessments. Announced as a staged plan in a Commission article of 7 July 2026, with no start date set. The press has called them “affordability checks”; the Commission’s own framework treats them as a distinct stage beyond the vulnerability check. They are announced and staged, not in force; the page does not pretend otherwise.
The named support services are worth knowing by name. GamCare runs the National Gambling Helpline. GambleAware funds treatment and education. The NHS runs gambling clinics in several regions. Gamblers Anonymous runs peer-support meetings. The British gambling industry funds GambleAware through a voluntary levy that has been the subject of political negotiation. None of these replaces the operator’s own safer-gambling tools, and the operator’s tools do not replace external help.
The safer-gambling tools at the operators reviewed further down include deposit limits, time-outs, product restrictions, self-exclusion and reality checks. Unibet’s UK site lists deposit limits, a Player Profile test, product restrictions and self-exclusion, with live-chat support and links to BeGambleAware, GamCare, GAMSTOP, Gambling Therapy and the Betting and Gaming Council. That list is the market standard rather than a one-off; the other operators in this guide cover the same set.
Mobile and apps: where most British punters bet
The bulk of British sports betting now happens on a handset. The Commission’s own data has tracked the shift from desktop and shop to mobile for the better part of a decade, and the licensed operators reviewed below all run iPhone and Android apps alongside their websites. The differences between operators on the handset are smaller than the marketing makes them sound. Most apps offer pre-match and in-play betting, a bet slip, cash out on selected markets, account management, deposit and withdrawal, and safer-gambling tools.
What does vary, and matters to a punter comparing brands:
- Live streaming. bet365 and Betfair are the long-standing reference points. William Hill’s WHTV requires a funded account or a bet in the last 24 hours, with live racing requiring a £1 bet on the qualifying race; Betting TV shows selected UK and US horse racing and UK greyhounds free. Unibet’s Unibet TV covers a similar set.
- Bet builder. Paddy Power’s Bet Builder+, bet365’s Bet Builder, Betfair’s Bet Builder, VBet’s Bet Builder, and Unibet’s Bet Builder all let the punter combine selections from one match into a single price. The mechanics differ — Paddy Power’s Super Sub rolls a bet over to the replacement if a selected player is substituted — but the principle is the same.
- Cash out. Available on most operators across most markets, with full and partial cash out. Coral offers cash out during races on its racing markets, which is a useful feature on busy Saturday afternoons.
- In-play markets. The depth varies by sport and by operator. Football and tennis are well covered across the licensed market; smaller sports have thinner coverage. The control is the operator’s licence conditions and customer-protection duties, not a statute, and in-play markets are not legally “unrestricted”.
- Stats and trackers. bet365’s Bet Track, Match Live and Live Golf Tracker are the most-cited examples. BetVictor’s Smart Stats and Paddy Power’s player and ACCA stats are part of the same family of features.
The browser experience still matters, partly because the apps do not always carry every market and partly because some punters bet on a laptop or a desktop. The ten operators reviewed below all run a full browser product alongside their apps.
What an AI prediction looks like on the handset
The mobile app is where most AI-driven tipsters and prediction services meet the British punter, and three patterns recur. The first is a dedicated tips app that sends selections to the punter’s phone, often through push notifications. The second is a website or Telegram channel that posts daily selections and asks for an affiliate click to a bookmaker. The third is a browser-based model whose output the punter reads on the same handset they place the bet on. All three depend on the punter checking the model’s record over a meaningful sample — at least a season, ideally two — before staking real money.
The free versions are free because the seller is paid by someone else, and that someone else is usually the bookmaker the tip is steering the punter towards. The affiliate disclosure on the tip page is the place to see who is paying. Subscription services sit behind a paywall and ask for a monthly or annual fee; the marketing on those pages is the only place a punter can see the claimed strike rate, the claimed yield and the sample size, and those three numbers need to be read together. A 70% strike rate over forty bets is a different claim from a 55% strike rate over four hundred, and the difference is the difference between a hot streak and a model.
Predictions and strategy: how a punter uses a model’s output
The marketing has spent the last few years selling the model as the answer. The honest answer is more modest. A model is a tool, and tools only do work in the hands of someone who knows what to ask of them. Five things are worth saying about how a punter uses an AI prediction, and none of them is the marketing.
Value, not picks
A prediction is a probability. A price is an implied probability. A value bet exists when the model’s probability is higher than the price’s implied probability, and that comparison is the bet, not the pick. A punter who backs every Arsenal selection the model flags without checking the price is doing the work of the model and skipping the work of the punter; the expected yield on that strategy is negative against the bookmaker’s margin. The discipline is the discipline of a value punter, and it is the same discipline whether the model is human or machine.
Sample size and strike rate
Strike rate is the number of winners divided by the number of bets. A model’s published strike rate over a small sample is not its real strike rate; the variance on fifty bets is wide enough to make any number misleading. The yardstick that matters is yield — the profit or loss per unit staked — and a meaningful yield number needs at least a season of data at a typical staking plan. Two-season data is better. Anything shorter is a taster, not a record.
Bankroll and staking
A bankroll is the amount of money a punter has set aside for betting and is prepared to lose. A flat stake of 1% to 2% of the bankroll per bet is the standard advice in the staking literature, and the standard advice is right: it keeps a bad week from wiping out the bankroll and lets the model’s edge play out over time. The discipline that the punter needs is the discipline of staking the same amount on each bet, regardless of how the previous bet went, and that discipline is harder than the model. A punter who doubles the stake after a loss is doing the work of the variance; a punter who increases the stake after a winning streak is doing the work of the recency bias.
Markets and where the model works best
Football, basketball and baseball are the sports where the data is densest and the models are most reliable. Horse racing and greyhound racing are the markets where the model competes against a market — the betting public, the form analysts and the on-course bookmakers — that has been pricing races with care for two centuries. The deeper the market, the harder it is for a model to find an edge, and the harder the edge is to verify. Niche sports and lower leagues are where the data is thinnest and where a single model with proprietary data has the best chance of finding a price the market has missed; they are also where a single bet the model has priced badly can blow up the staking plan.
Discipline, not the model
The most underrated variable in punting is the punter. A model that is 55% right at 2.00 prices over a season is in profit. The punter who bets on the model’s tips, skips the ones they do not like, doubles the stake after a loss, and chases the missed weekend’s selections on a Monday is the punter who turns a profitable model into a losing bankroll. The bookmaker’s margin is patient. The variance runs — it does not negotiate. The discipline is the discipline of reading the price, sizing the stake and walking away from the bet the model flags when the price is wrong.
A worked illustration of the margin
A two-way market priced at 1.90 / 1.90 carries an implied probability of about 52.6% on each side, because 1 ÷ 1.90 = 0.5263. Add the two implied probabilities and the sum is 1.0526 — a hair over 1, and the difference between 1 and the sum is the bookmaker’s margin. The margin on this market is 1 − (1 ÷ (1 ÷ 1.90 + 1 ÷ 1.90)) = 1 − 0.9524 ≈ 4.76%.
A more realistic market with a stronger favourite — 1.40 / 3.00 — has implied probabilities of 71.4% and 33.3%, summing to 1.047, so the overround sits around 4.7% and the margin at 4.5%. Move to a three-way football market at 1.85 / 3.40 / 4.50, and the implied probabilities are 54.1% / 29.4% / 22.2%, summing to 1.057, which puts the overround at 5.7% and the margin at roughly 5.4%. The margin is not a single number across the bookmaker’s book. It is a feature of each market, and the punter who reads it is the punter who can spot when a price is generous.
The calculation is illustrative rather than quoted, because the prices named above are an example, not a snapshot from any one bookmaker. A real market at any operator will price closer or wider depending on the sport, the event and the bookmaker’s book. The takeaway is structural: the margin is always there, always positive, and always a slice of every unit the punter stakes.
The ten operators, ranked and compared
The list below covers ten operators that hold a Gambling Commission remote general betting licence for real events and serve British customers. The order is editorial and reflects how the operators sit against the matters a punter weighing them against each other needs to see. Each entry names the brand, what sets it apart in the comparison, the Gambling Commission licence holder and account number, and what the operator’s own terms say on the matters that recur across the ranking. None of these operators is “the only” licensed brand — the Commission’s register lists many others — and the ranking is a shortlist rather than a recommendation.
The table that follows is the page’s reference point. It is short on purpose. Each row is a brand; each column is a matter the table is built to compare. The columns are named below the table.
| Brand | Licence holder | Commission account | What the operator’s own terms state on AI predictions |
|---|---|---|---|
| BetGoodwin | Goodwin Racing Limited | 2927 | Racing-focused sportsbook with Best Odds Guaranteed on UK and Irish horse and greyhound racing, up to £1,000 |
| Betway | Betway Limited | 39372 | Welcome package £40 in free bet tokens (4 × £10) on settlement of a first bet of at least £10 at minimum odds of 2.0, with a 7-day expiry and debit-card deposits only |
| bet365 | Hillside (UK Sports) ENC | 55148 | In-play betting, live streaming of events worldwide, plus Bet Track, Match Live and a Live Golf Tracker for following bets in play |
| William Hill | WHG (International) Limited | 39225 | Best Odds Guaranteed on UK and Irish horse racing from 8am on race day, on single and multiple bets; WHTV streaming with the conditions named above |
| Lottoland | EU Lotto Limited | 38991 | Combines casino, lottery betting, sports betting and scratchcards; licensed by the Commission for customers in Great Britain |
| VBet | SCGO Limited | 44662 | Bet Builder, pre-match and in-play betting, live streaming and a live calendar with results and stats |
| Midnite | Midnite Limited | 101839 | In-play events, an acca builder, popular accas and price boosts with maximum-stake limits; sports welcome offer as named in the write-up |
| Sky Bet | SBG Sports Limited | 67370 | Welcome package £30 in free bets as three £10 tokens after a £5 deposit and a first single or each-way bet of at least 5p at odds of 1/1 or greater |
| Tote | TDCO Limited | 54779 | Pool betting heritage on horse racing; pool and fixed-odds coverage on a single brand |
| Paddy Power | PPB Counterparty Services Limited | 39439 | Bet Builder+, Popular Bet Builders, Super Sub substitution rollover, expanded Win More markets, and player and ACCA stats |
Two matters the table leaves out are worth flagging. The first is the AI-prediction tooling at the operator itself. None of these brands publishes a proprietary model; the operator’s role is to price markets and accept bets, and any AI work the punter does sits at the punter’s end of the trade. The second is the affiliate tipster the punter might pair with the operator — those services live outside the Commission’s register and the table is not the place for them. The table is the licensed operators’ terms on their own products, and that is where its honesty lies.
BetGoodwin — the racing-led shortlist
BetGoodwin is run by Goodwin Racing Limited on a Commission account number of 2927, with remote general betting standard (real events) as its registered category. The brand is racing-led: its Best Odds Guaranteed covers all UK and Irish horse and greyhound racing up to £1,000, and the welcome offer is built around the racing product rather than the football product. The promise is a simple one — if the starting price is bigger than the price the punter took, BetGoodwin pays the bigger one, and that promise is the line on which racing punters compare books.
For the racing punter, BetGoodwin is the closest match to the product they want to bet on. For the football punter, the brand is a less obvious fit, because the football coverage is not where the brand has built its reputation. The licence and the safer-gambling tools are the market standard; the welcome offer rewards a first racing bet rather than a first sports bet.
Betway — the long-standing mainstream
Betway is run by Betway Limited on a Commission account number of 39372. The welcome offer for new UK and Ireland customers is £40 in free bet tokens (4 × £10), credited on settlement of a first bet of at least £10 at minimum odds of 2.0, with a 7-day expiry and debit-card deposits only. The free-bet tokens are stake-not-returned, which is the standard free-bet mechanic: the punter keeps the winnings, not the stake, and the small print on the expiry is the place to read before claiming.
The brand’s coverage is broad, and the app is well-established on the British market. The welcome package offers clarity: a known stake, a known minimum price, a known expiry, and a payment-method restriction. The same clarity is the reason the small print reads small; the punter who reads it before claiming is the punter who does not lose the free bet to expiry.
bet365 — the in-play reference
bet365 is run by Hillside (UK Sports) ENC on a Commission account number of 55148. The brand sets the reference on in-play markets and on live streaming, and the app’s supporting features — Bet Track, Match Live and the Live Golf Tracker — are the long-running answer to the question “how do I follow a bet once the event has started”. The depth of in-play markets across football, tennis, basketball and the US sports is the reason the brand has the mindshare it has, and the streaming product is the reason the in-play product is usable.
For the punter whose betting is in-play-led, bet365 is the reference on the list and the comparison point the others are measured against. The welcome offer’s structure is the brand’s own — it changes through the year and is described in the app’s promotional terms rather than a single page — and the safer-gambling tools are the market standard. The product’s strength is also its dependency: the in-play and streaming features work best on the app, and the punter who bets on the browser is using a thinner version of the brand.
William Hill — the high-street heritage
William Hill is run by WHG (International) Limited on a Commission account number of 39225. The Best Odds Guaranteed on UK and Irish horse racing applies from 8am on the day of the race, on both single and multiple bets, and does not apply to ante-post, tote or pari-mutuel bets. The streaming product — WHTV — requires a funded account or a bet in the last 24 hours; live racing requires a £1 bet on the qualifying race, and Betting TV shows selected UK and US horse racing and UK greyhounds free.
The heritage reads in the high-street shop count and the brand recognition rather than in any single product feature, but the racing product is the line the brand has built on. The BOG coverage and the streaming under one roof provide the value, and the small print on the streaming — the funded-account or qualifying-bet requirement — is where the value lives or does not.
Lottoland — the lottery-rooted shortlist
Lottoland is run by EU Lotto Limited on a Commission account number of 38991. The product combines casino, lottery betting, sports betting and scratchcards, and the brand states it is licensed by the Commission for customers in Great Britain. The lottery betting product is the line the brand was built on, and the sportsbook is a more recent addition.
For a punter whose betting is sports-led, Lottoland is the name on this list that splits attention across more product categories than the others, and the sports coverage is not the long-standing reference in the same way that bet365’s is. The welcome offer is described in the app’s promotional terms rather than on a single page. The licence is current on the Commission’s register, and safer-gambling protections are integrated into the platform.
VBet — the feature-led shortlist
VBet is run by SCGO Limited on a Commission account number of 44662. The app offers Bet Builder, pre-match and in-play betting, live streaming and a live calendar with results and stats, and the product set is broad across football, racing, tennis and US sports. The live calendar is the feature the brand has put at the front of its product, and the bet builder is the workhorse feature for football-led punters.
VBet’s live calendar’s integration with the in-play markets and the bet builder’s range across leagues are the central features. The welcome offer’s structure is the brand’s own, and the safer-gambling tools are the market standard. The product’s depth across the European football leagues is the line the brand has built on.
Midnite — the newer entrant
Midnite is run by Midnite Limited on a Commission account number of 101839. The site cites the licence and shows in-play events, an acca builder, popular accas and price boosts with maximum-stake limits. The welcome offer is the brand’s own: new customers who bet £5 or more on pre-match odds of EVS (2.0) or greater within 14 days of sign-up receive £25 in free bets and 50 free spins, valid for 7 days. The free-bet portion is stake-not-returned, which is the standard free-bet mechanic.
For the punter weighing Midnite against the rest of the list, the value proposition is the welcome offer’s low entry stake — £5 qualifying bet. The maximum-stake limits on price boosts are the small print the punter reads before claiming, because the boost is worth more on a bigger stake than the boost’s headline.
Sky Bet — the broadcaster-rooted brand
Sky Bet is run by SBG Sports Limited on a Commission account number of 67370. The welcome offer for new customers is £30 in free bets, credited as three £10 free bet tokens after a deposit of at least £5 and a first single or each-way bet of at least 5p at odds of 1/1 or greater. The minimum stake of 5p is the entry-level condition across the licensed market, and the minimum odds of 1/1 (2.0) is the standard minimum for the welcome offer’s qualifying bet.
Sky Bet’s welcome offer features an entry-level stake and the brand’s coverage of football and racing. The brand is rooted in the broadcaster rather than the bookmaker heritage, and safer-gambling tools form a core part of the experience. The price boost on selected football accas is the small print the punter reads before staking.
Tote — the pool-betting heritage
Tote is run by TDCO Limited on a Commission account number of 54779. The brand is the British pool-betting institution, and the product set covers pool and fixed-odds markets on horse racing in particular. The pool product is a different proposition from the fixed-odds book, because the dividend depends on the pool’s stake and the winners rather than on the bookmaker’s margin on a single race.
Tote’s pool product on racing is the line the brand has built on for the better part of seven decades. The fixed-odds sportsbook is a more recent addition.
Paddy Power — the marketing-led brand
Paddy Power is run by PPB Counterparty Services Limited on a Commission account number of 39439. The brand runs Bet Builder+, Popular Bet Builders, Super Sub (a bet rolls over to the replacement if a selected player is substituted), expanded Win More markets and player and ACCA stats. The product is football-led, and the marketing has been the loudest in the licensed market for years.
Paddy Power’s bet builder’s depth and the Super Sub’s protection against the most common cause of a settled losing bet on a player market are the main draws. The marketing sets a high bar that the product has to clear, and operators must follow strict safer-gambling licence conditions. The licence is current on the Commission’s register; Paddy Power and Betfair share a parent and are licensed separately.
The pages a punter reads next
Two further pieces of work sit behind any punter weighing AI predictions seriously. The first is the punter’s own record. A spreadsheet of bets, odds, result, profit and loss, kept across at least a season, is the only way a punter knows whether the strategy they are running is making or losing money. A model that is supposed to make 5% on turnover over a season and is flat after six months is not a model to follow; a model that is supposed to be flat and is ahead after six months is a model to follow more closely.
The second is the small print at the operator the punter is using. The wagering multiple on the welcome bonus, the minimum price for the qualifying bet, the expiry on the free bet, the cap on winnings from a free bet, the minimum deposit, the payment-method restriction and the maximum stake on the price boost are the seven numbers a punter reads before claiming. None of them are negotiable. The punter who reads them is the punter who does not lose the offer to expiry or disqualify the qualifying bet by one tick of odds.
The third, and the one the marketing skips, is the limit on offers at the punter’s own end. A bankroll is the money the punter is prepared to lose. A flat stake of 1% to 2% of the bankroll per bet is the staking plan that lets a model’s edge play out. A deposit limit at the operator, set by the punter before the welcome offer rather than after, is the safer-gambling control that keeps the staking plan honest. None of this is the model’s work. All of it is the punter’s work, and the punter is the only one who can do it.
Frequently asked questions
Can AI help with betting?
Yes, in the sense that a model can process more fixtures, more form data and more line-up information than a human can read in a week, and produce a probability for each outcome that the punter can compare to the bookmaker’s price. The model is a faster reader of data, not a predictor of results. The punter’s discipline is comparing the model’s probability to the price, sizing the stake, and accepting that even a strong probability will lose three or four times in ten. A model that helps is a model the punter uses as a tool, not a model the punter follows as a tip sheet.
Can AI help with sports betting?
Yes, with the same caveat. The narrower the market — a specific league, a specific match type — the better the model tends to fit, because the data is denser and the variance is smaller. The wider the market — every Premier League game in a weekend — the more the model is averaging across fixtures, and the more the punter’s job is picking the ones where the model’s probability sits above the price’s implied probability. A punter using AI for sports betting should keep a record of bets placed, the model’s probability and the price taken, so that the yield on the strategy is known.
Can AI predict sports betting?
Predict, in the sense of forecasting a single fixture’s outcome with certainty, no. A model assigns probabilities. A probability is not a prediction in the colloquial sense, because the punter who treats the model’s 60% as a guarantee will lose on the 40% and complain that the model is broken. A punter who treats the 60% as a bet at the right price will lose three or four times in ten, on average, and that loss is the cost of admission to the 60% over a season.
What is a value bet and why is no tip ever certain?
A value bet is a price that is bigger than the probability the model assigns to the outcome, and the comparison is the bet. No tip is certain because every bet has a losing outcome: a 70% favourite loses three times in ten on average, and the variance around the average is the reason a punter’s record over a season is the only number that matters. The marketing wants certainty. The maths offers probability. The punter who accepts the maths is the punter who survives the variance.
What is the bookmaker’s margin and how can it be seen in the odds?
The margin is the slice of every unit staked that the bookmaker keeps, on average, across a market. It can be seen by adding the implied probabilities of every outcome of the market — for a two-way market priced at 1.90 / 1.90, the sum is about 1.05, so the margin is about 5%. The bigger the sum, the bigger the margin, and the harder the punter has to work to find a value bet. The margin is the cost of placing a bet, and the punter who reads it is the punter who knows what the bet costs.
How is the return on a bet worked out from the stake and the odds?
For a single bet, the return is the stake multiplied by the decimal odds, and the net profit is the stake multiplied by the odds minus one. A £10 bet at 3.00 returns £30 and pays £20 in profit; the same stake at 1.50 returns £15 and pays £5 in profit. For a combination bet — a double, treble or accumulator — the odds of each leg multiply into one price, and the return is the stake multiplied by the combined price. The combined price is the price the punter reads on the bet slip before confirming the stake.
Tips & predictions – Bookies Trust
Content created by the «Bookies Trust» team
